قياس أثر مخاطر الائتمان على جودة المعلومات المحاسبية: دراسة مقارنة بين مصرف كردستان الدولي الإسلامي للاستثمار والتنمية والمصرف الإسلامي العراقي
الشريط الجانبي للمقالة
THIS IS AN OPEN ACCESS ARTICLE UNDER THE CC BY LICENSE
محتوى المقالة الرئيسي

الملخص
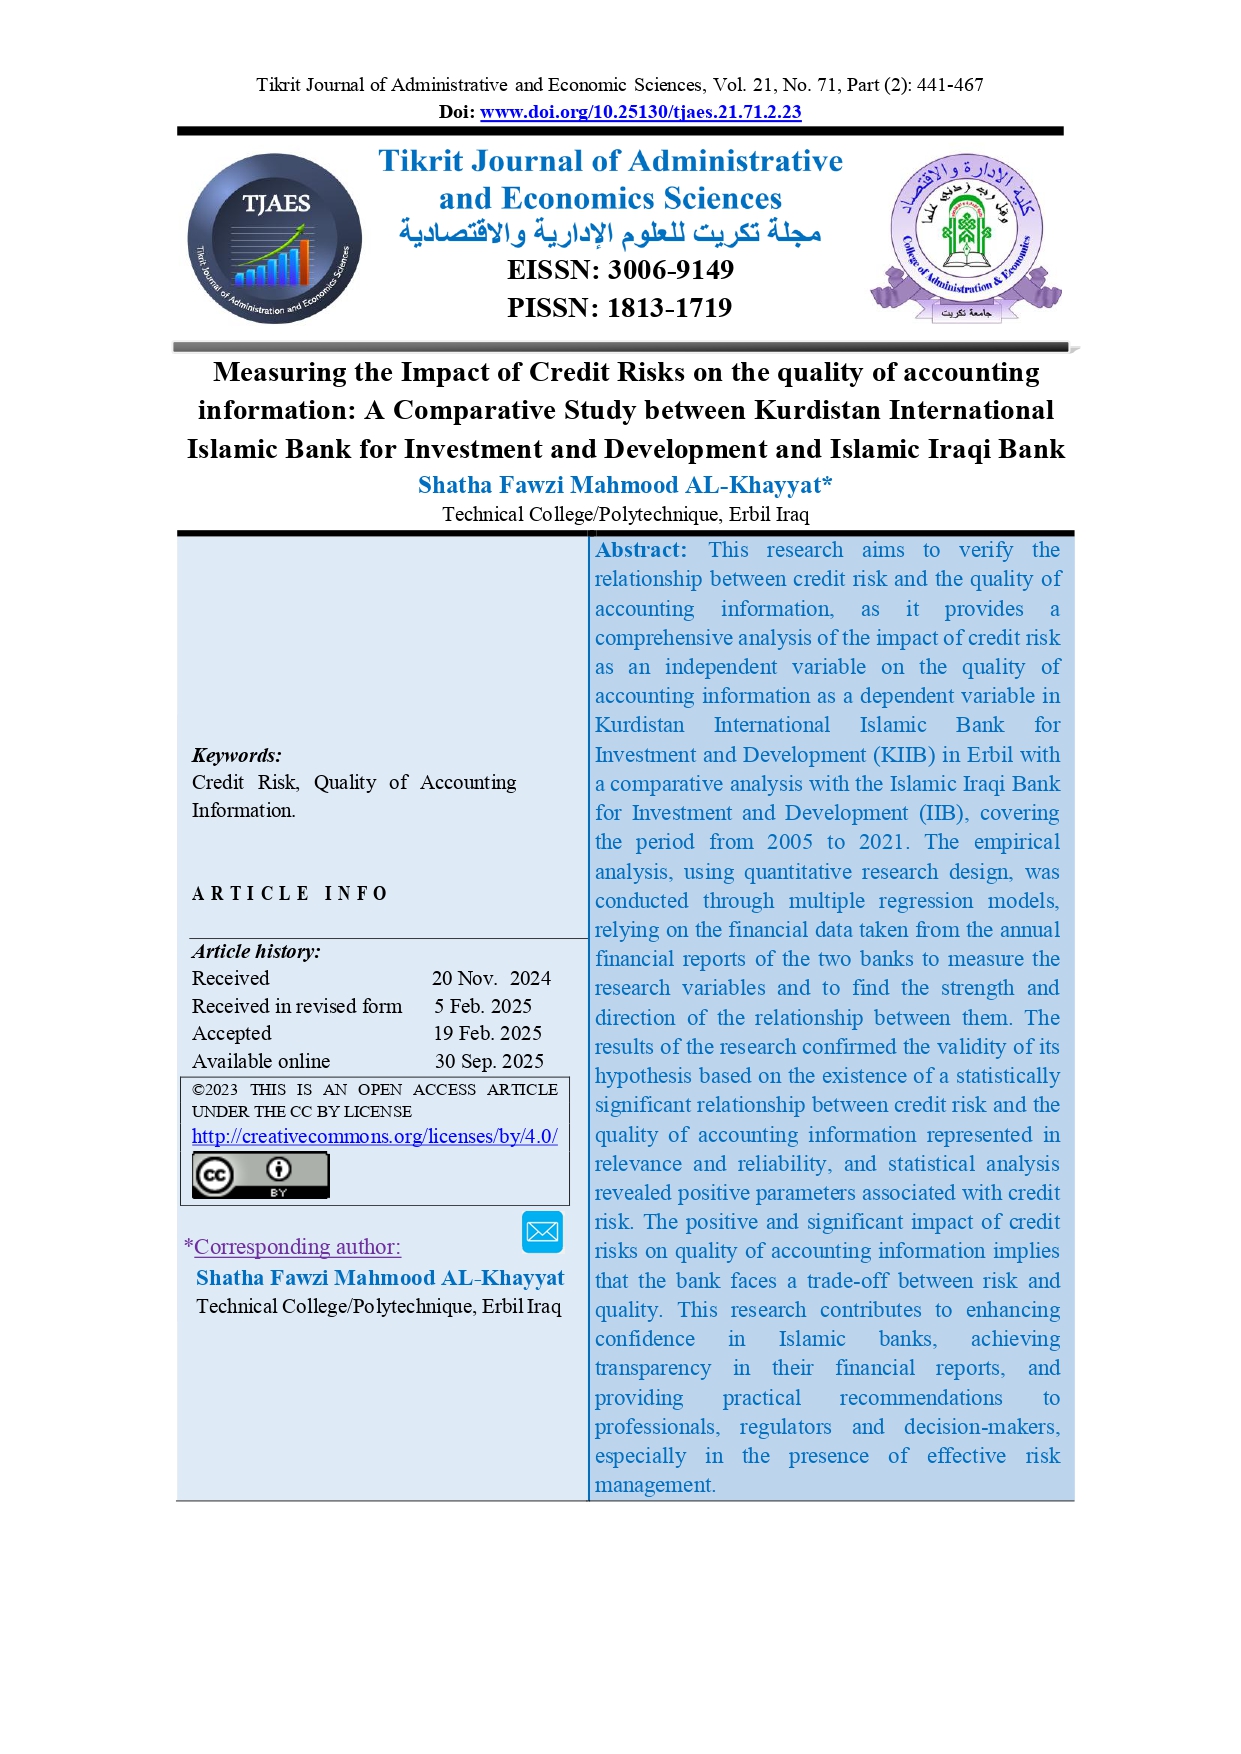
يهدف هذا البحث إلى التحقق من العلاقة بين مخاطر الائتمان وجودة المعلومات المحاسبية، حيث يقدم تحليلاً شاملاً لتأثير مخاطر الائتمان كمتغير مستقل على جودة المعلومات المحاسبية كمتغير تابع في بنك كردستان الدولي الإسلامي للاستثمار والتنمية (KIIB) في أربيل مع تحليل مقارن مع البنك الإسلامي العراقي للاستثمار والتنمية (IIB)، والذي يغطي الفترة من 2005 إلى 2021. تم إجراء التحليل التجريبي باستخدام تصميم البحث الكمي من خلال نماذج الانحدار المتعدد، بالاعتماد على البيانات المالية المأخوذة من التقارير المالية السنوية للبنكين لقياس متغيرات البحث وإيجاد قوة واتجاه العلاقة بينهما. أكدت نتائج البحث صحة فرضيته القائمة على وجود علاقة ذات دلالة إحصائية بين مخاطر الائتمان وجودة المعلومات المحاسبية المتمثلة في الملاءمة والموثوقية، وكشف التحليل الإحصائي عن معايير إيجابية مرتبطة بمخاطر الائتمان. إن التأثير الإيجابي والهام لمخاطر الائتمان على جودة المعلومات المحاسبية يعني أن البنك يواجه مقايضة بين المخاطر والجودة. يُسهم هذا البحث في تعزيز الثقة بالمصارف الإسلامية، وتحقيق الشفافية في تقاريرها المالية، وتقديم توصيات عملية للمختصين والجهات الرقابية وصناع القرار، لا سيما في ظل وجود إدارة فعّالة للمخاطر.
التنزيلات
تفاصيل المقالة
المراجع
Acharya, V., Engle, R., & Richardson, M. (2012). Capital shortfall: A new approach to ranking and regulating systemic risks. American Economic Review, 102(3), 59-64.
Ahmed, E. (2021). Analysis the relationship between the extent of risk disclosure in financial reports and the company's risks and its reflection on earnings management - An applied study on Saudi Stock Market listed companies. Scientific Journal of Commercial and Environmental Studies, 12(3), 217-292.
Al-Tamimi, H. A. H., & Al-Mazrooei, F. M. (2007). Banks’ risk management: A comparison study of UAE national and foreign banks. The Journal of Risk Finance, 8(4), 394-409.
Al-Khayyat, S., Sharofiddin, A., & Al-Shaghdari, F. (2024). Analyzing and Measuring the Impact of Operational Risks On Earning Management: An Applied Study On Islamic Banks Listed on the Iraq Stock Exchange for The Period (2011-2021). al-Qanatir: International Journal of Islamic Studies, 33(6), 196-211.
Altman, E. I., & Saunders, A. (1998). Credit risk measurement: Developments over the last 20 years. Journal of Banking & Finance, 21(11-12), 1721-1742.
Al-Naami, Ali Suleiman and Ahmed Brik Al-Amawi. (2015). The Role of Institutional Control Pillars in Activating Banking Risk Management "An Applied Study on Palestinian Banks in Gaza Governorate - Palestine". Journal of the University of Palestine for Research and Studies. Issue Eight, Part One.
Al-Hamidawi, Ali Hussein Mahawesh. (2016). The impact of changes in the conceptual framework of financial accounting on Iraqi accounting practices. Unpublished Master's Thesis, Wasit University, Iraq, p. 39.
Armouti, Ahmed Adnan. (2013). The Impact of Sustainability Accounting on Financial Reporting in Jordanian Public Shareholding Industrial Companies Listed on the Amman Stock Exchange. Master Thesis, Middle East University, Faculty of Commerce.
Ball, R., & Shivakumar, L. (2005). Earnings Quality in UK Private Firms: Comparative Loss Recognition Timeliness. Journal of Accounting and Economics, 39(1), 83-128.
Ball, R. (2006). International Financial Reporting Standards (IFRS): Pros and Cons for Investor (pp. 5-27). In Accounting and Business Research International Accounting Policy Forum. https://doi.org/10.1080/00014788.2006 (Vol. 9730040).
Barth, M. E., Beaver, W. H., & Landsman, W. R. (2001). The relevance of the value relevance literature for financial accounting standard setting: Another view. Journal of Accounting and Economics, 31(1-3), 77-104.
Barth, M. E., Landsman, W. R., & Lang, M. H. (2008). International accounting standards and accounting quality. Journal of accounting research, 46(3), 467-498.
Basel Committee on Banking Supervision. (2011). Basel III: A global regulatory framework for more resilient banks and banking systems. Bank for International Settlements.
Beatty, A., & Liao, S. (2014). Financial accounting in the banking industry: A review of the empirical literature. Journal of Accounting and Economics, 58(2-3), 339-383.
Bholat, D., Lastra, R., Markose, S., Miglionico, A., & Sen, K. (2018). Non-performing loans at the dawn of IFRS 9: Regulatory and accounting treatment of asset quality. Journal of Banking Regulation, 19(1), 33-54.
Bushman, R. M., & Williams, C. D. (2015). Accounting discretion, loan loss provisioning, and discipline of banks’ risk-taking. Journal of Accounting and Economics, 54(1), 1-18.
Beatty, A. L., Ke, B., & Petroni, K. R. (2002). Earnings management to avoid earnings declines across publicly and privately held banks. The accounting review, 77(3), 547-570.
Chen, A., & Gong, J. J. (2019). Accounting comparability, financial reporting quality, and the pricing of accruals. Advances in accounting, 45, 100415.
Cohen, J., Krishnamoorthy, G., & Wright, A. (2017). Enterprise risk management and the financial reporting process: The experiences of audit committee members, CFO s, and external auditors. Contemporary Accounting Research, 34(2), 1178-1209.
Dechow, P. M., Sloan, R. G., & Sweeney, A. P. (1995). Detecting earnings management. Accounting review, 193-225.
Dechow, P., & Dichev, I. (2002). The Quality of Accruals and Earnings: The Role of Accrual Estimation Errors. The Accounting Review,77, 35-59.
DeFond, M. L., & Zhang, J. (2014). A review of archival auditing research. Journal of Accounting and Economics, 58(2-3), 275-326.
Doyle, J. T., Ge, W., & McVay, S. (2007). Accruals quality and internal control over financial reporting. The accounting review, 82(5), 1141-1170.
FASB (Financial Accounting Standards Board). (2018). Conceptual Framework for Financial Reporting. Retrieved from [FASB website] (https://www.fasb.org).
Francis, J., LaFond, R., Olsson, P. M., & Schipper, K. (2004). Costs of equity and earnings attributes. The accounting review, 79(4), 967-1010.
Graham, J. R. (1999). Do Personal Taxes Affect Corporate Financing Decisions? Journal of Public Economics73.2, 147-185.
Guay, W. (1999). The Sensitivity of CEO Wealth to Equity Risk: An Analysis of the Magnitude and Determinants. Journal of Financial Economics.
Ivashina, V., & Scharfstein, D. (2010). Bank lending during the financial crisis of 2008. Journal of Financial economics, 97(3), 319-338.
Islamic Financial Services Board. (2005). Risk Management Guidelines for Institutions (other than Insurance Institutions) that are limited to the provision of Islamic financial services. Takaful and Islamic Investment Funds, pp. 11-44.
IASB (International Accounting Standards Board). (2018). Conceptual Framework for Financial Reporting. Retrieved from [IASB website] (https://www.ifrs.org).
Jones, J. (1991). Earnings Management During Import Relief Investigations. Journal of Accounting Research,29(2), 193-228.
Jensen, M. C., & Meckling, W. H. (2019). Theory of the firm: Managerial behavior, agency costs and ownership structure. In Corporate governance (pp. 77-132). Gower.
Kim M, Kross W (1998) The impact of the 1989 change in bank capital standards on loan loss provisions and loan write-offs. Journal of Accounting and Economics, 25(1):69–99.
Khansalar, E. (2012). The reliability of accruals and the prediction of future cash flow. International Journal of Business and Management, 7(2), 45-57.
Kythreotis, A. (2014). Measurement of financial reporting quality based on IFRS conceptual framework's fundamental qualitative characteristics. Kythreotis, A. (2014)." Measurement of Financial Reporting Quality Based On Ifrs Conceptual Framework’ S Fundamental Qualitative Characteristics," European Journal of Accounting, Finance & Business, 2(3), 4-29.
Kieso, Donald.E., Weygandt, Jerry. J., & Warfield, Terry. D. (2020). Intermediate Accounting, john & sons inc 4th edition, United states of America.
Laeven, L., & Majnoni, G. (2003). Loan loss provisioning and economic slowdowns: Too much, too late? Journal of Financial Intermediation, 12(2), 178-197.
Monjed, H.& Ibrahim, S. (2020). Risk disclosure, income smoothing and firm risk. Journal of Applied Accounting Research, 21(3), 517-533.
Mahmoud, Jamam. (2016). The Impact of Accounting Information Quality on Investment Decision Making, A Study of a Sample of Economic Institutions in the Wilayat of Constantine, Algeria. Journal of Baghdad College of Economic Sciences University. Issue 47.
Supervision, B. (2011). Basel committee on banking supervision. Principles for Sound Liquidity Risk Management and Supervision (September 2008).
Yaaqoub B., Ibtihaj Ismail and Jassim, Abdul Reda Latif. (2018). Testing the impact of switching to standards International Financial Reporting IFRS on the private banking sector in the Iraqi environment from the perspective of Qualitative and Values, Journal of Management and Economics D, Al-Mustansiriya University, Iraq, Issue (114,) P214.